Key takeaways
- The UK’s CARF rules took effect on 1 January 2026, with first provider reports to HMRC for the 2026 calendar year due by 31 May 2027.
- India’s CBDT issued a guidance note on 24 July 2026 on crypto-asset reporting under the Income-tax Act, 2025; its international exchange date is reported differently.
- Your Indian exchange will ask for a self-certification of tax residence, and a wrong answer can send your data to the wrong country.
- Report Indian crypto gains in the UK, convert to pounds, and take UK and Indian advice on relief.
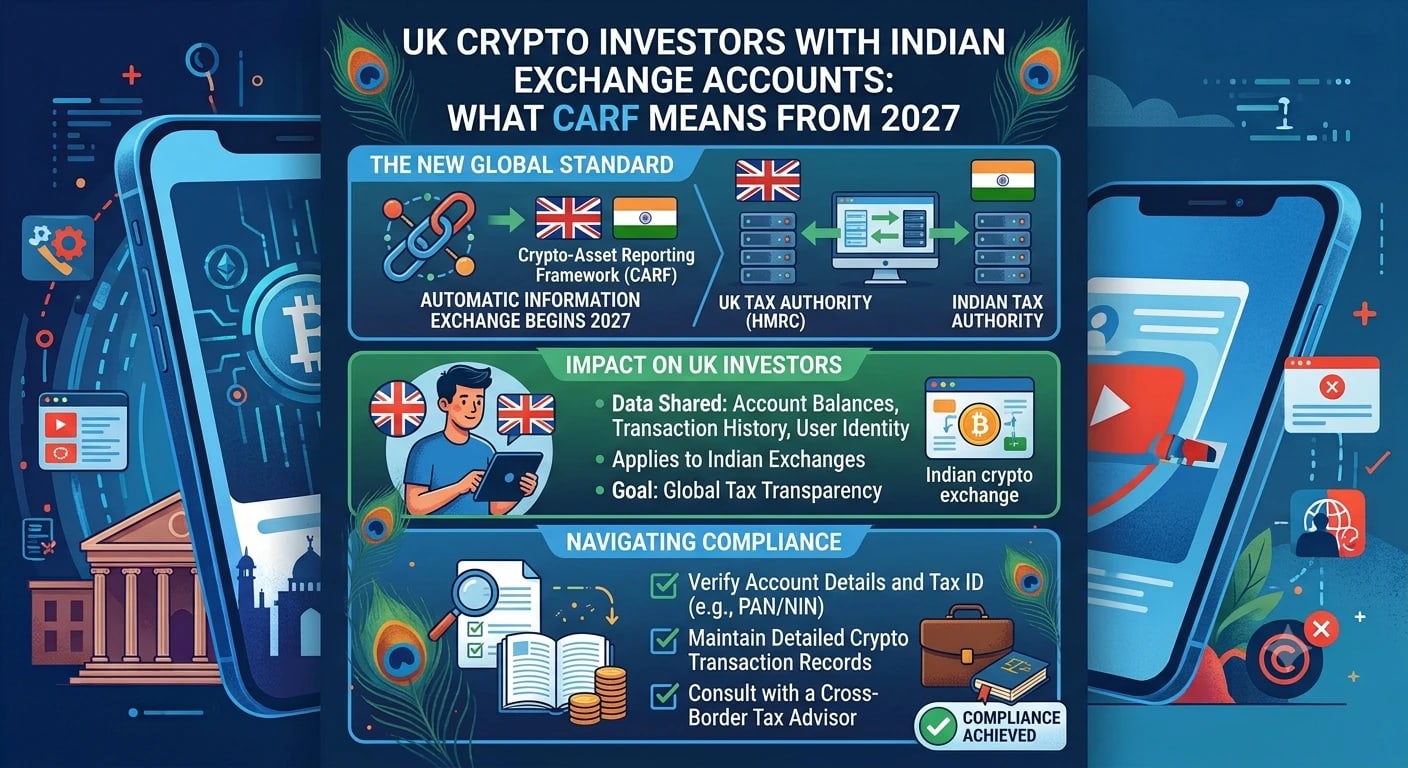
If you live in the UK and keep crypto on an Indian exchange, tax authorities in both countries will soon be able to compare notes. The OECD’s Crypto-Asset Reporting Framework, known as CARF, makes crypto platforms collect your tax residence and transaction data and report it, and countries then exchange that data. For CARF UK India crypto holders, the first exchanges between tax authorities are due to begin in 2027.
This guide explains how CARF works, the UK dates, India’s own reporting, what your Indian exchange may ask you, how HMRC and the Indian tax department could end up with the same data and what to do before the first reports. It is written by an Indian law firm. UK tax points should be confirmed with a UK adviser, and exchange of information dates should be checked with official sources.
What CARF does
CARF is a global standard that requires crypto-asset service providers to identify their customers’ tax residence, collect details of reportable transactions and report them to their local tax authority. That authority then exchanges the data with the customer’s country of residence. It works like the Common Reporting Standard for bank accounts, but for crypto exchanges, brokers and some wallet services. For UK residents, CARF UK India crypto reporting works through the platform you use.
The data covers exchanges between crypto and fiat money, exchanges between different crypto-assets, transfers and certain retail payments. It is reported in totals for each type of transaction. The aim is to remove the gap in which crypto gains on a foreign platform were invisible to the investor’s home tax authority. UK residents who hold accounts abroad are within the intended scope.
CARF affects individuals through the platform, not directly. You do not file a CARF form. You complete a self-certification when you open or update an account, stating where you are tax resident. The platform uses that information to decide where to send your data. So the CARF UK India crypto position turns on what your Indian exchange knows about your residence and what the Indian tax authority later shares. Answering the CARF self-certification UK investors face is the single most important step.
UK and Indian dates
The UK adopted CARF through regulations that took effect on 1 January 2026. UK crypto-asset service providers began collecting user and transaction data from that date, and their first reports to HMRC, covering the 2026 calendar year, are due by 31 May 2027. HMRC will exchange data with partner countries that have also implemented the framework. Check HMRC’s guidance for the current partner list. The CARF first reports 31 May 2027 date is the one to diarise. The CARF UK India crypto timetable has two clocks, one in each country.
| Item | UK | India |
|---|---|---|
| Data collection starts | 1 January 2026 | Domestic reporting reported from 1 April 2026 |
| First reports | 31 May 2027, for the 2026 calendar year | Form 167 statements under Section 509 |
| International exchange | Partner countries that have implemented CARF | Reported start differs, some say 2027 |
| Your action | Self-certify tax residence accurately | Update the exchange and keep records |
India has its own timetable. The Central Board of Direct Taxes issued a guidance note on 24 July 2026 on crypto-asset reporting by reporting service providers, under Section 509 of the Income-tax Act, 2025, with reporting in Form 167. Domestic reporting is reported to have started from 1 April 2026. Reports differ on when India will start exchanging data with other countries under CARF, with some pointing to 2027 and others later.
Treat the dates as a planning window, not a guarantee. If your Indian exchange reports you as a UK tax resident, that data could reach HMRC once India begins exchanging, and in the meantime HMRC may receive data about you from UK platforms and from other countries that have started earlier. Waiting for the first exchange to tidy up your position is a poor strategy, since mistakes will be visible from several directions. HMRC crypto data sharing India may begin only when both countries exchange, but UK platforms report sooner.
What data moves and what you will be asked
A reporting platform collects your name, address, date of birth, tax residence and tax identification number, such as your UK National Insurance or Unique Taxpayer Reference. It reports the type of crypto-asset, the number of units and the gross proceeds or cost of reportable transactions. It does not usually report your wallet balance, but it may report transfers to and from your account.
When you open or update an account, expect a self-certification form. It asks you to state each country where you are tax resident and to give your tax identification numbers. Answer accurately. A false self-certification can lead to penalties for the platform and for you, and a wrong answer can send your data to the wrong country. If you moved to the UK recently, update the exchange so that its records match your status.
Indian exchanges are already asking for more information from users. If you are a UK resident with an Indian account, you may be asked for proof of address, a tax identification number and a declaration about your residence. Respond promptly, and keep copies. If an Indian exchange restricts your account for incomplete information, you may need to supply documents quickly to avoid a freeze.
Tax consequences for UK residents with Indian accounts
UK residents are generally taxed on gains from disposals of crypto anywhere in the world, using the UK rules for Capital Gains Tax, including pooling and matching rules. Gains on an Indian exchange must therefore go on your UK Self Assessment return, converted to pounds. Check the rules for people who recently arrived in the UK, as special regimes apply to some new residents. That is the practical meaning of CARF UK India crypto reporting for your tax return.
India may also tax your gains. If you are non-resident in India, India taxes only Indian-source income, and the treatment of gains on an Indian exchange can depend on the facts. Indian rules charge a 30% tax on virtual digital asset gains with a 1% TDS on transfers. The India-UK double taxation treaty and UK foreign tax credit rules may give relief, but the treatment of crypto is not settled, so take advice from both countries.
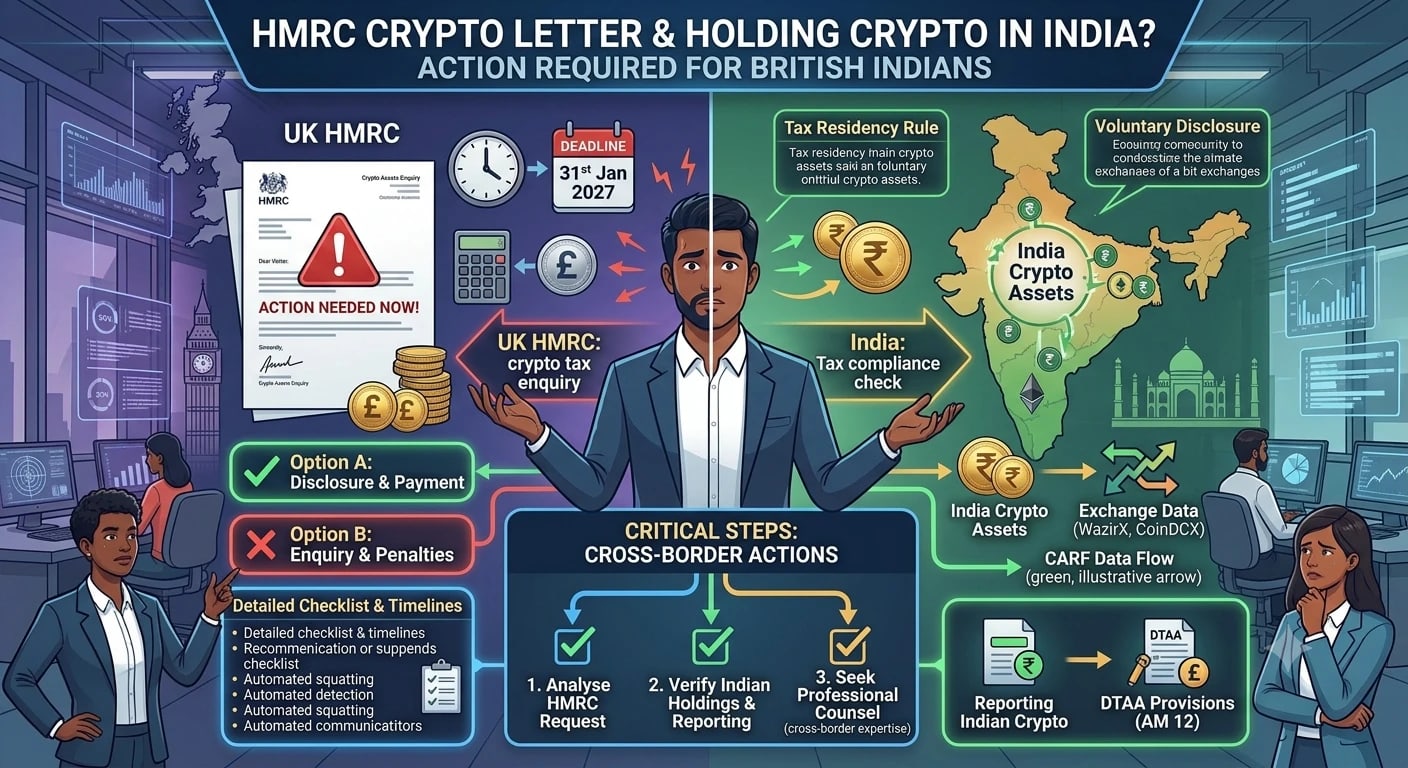
If you have not reported Indian crypto gains in the UK, consider correcting your position. HMRC’s disclosure routes usually give better outcomes than waiting for a letter, and HMRC has sent tens of thousands of crypto nudge letters. Gather your Indian exchange statements now, because those records may be harder to obtain later if the account is restricted. Treat CARF as a prompt to update your records in both countries. Remember to report Indian crypto on UK tax return forms for every year concerned.
Next steps and quick answers
Do four things this month: list every exchange and wallet, download your Indian exchange statements, work out your UK and Indian tax positions and update each platform with your correct tax residence. Speak to a UK tax adviser about disclosure if you have gaps. This is general information, not tax advice. A UK resident Indian exchange account tax review should list every disposal. Make CARF UK India crypto preparation a standing task.
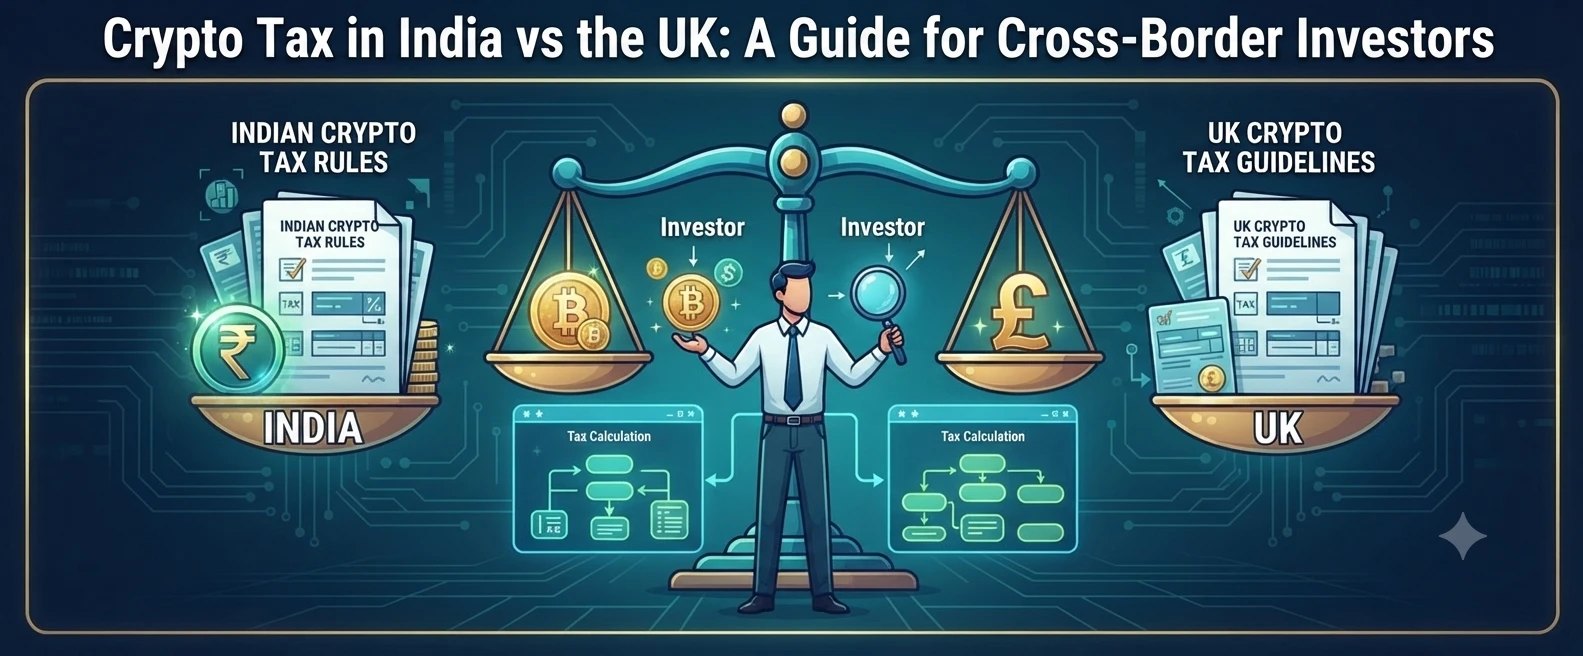
Related reading: the HMRC crypto letter and Indian crypto holdings, crypto tax in India and the UK compared, UK crypto exchanges and Indian users: FIU-IND and tax, what CARF means for Indian expats in Dubai, what Budget 2026 changed for crypto tax, FIU-IND registration for crypto businesses and the crypto nudge email from the tax department; also CARF reporting for the UAE and India and crypto tax in the UK for Indian students; also UK CARF crypto reporting.
Quick answers
What does CARF mean for a UK resident with an Indian exchange account?
Your Indian exchange will collect your tax residence and transaction data, report it to the Indian tax authority and, once India starts exchanging, that data may reach HMRC. UK platforms must also report to HMRC from 2027.
When are the first CARF reports due in the UK?
UK crypto-asset service providers began collecting data on 1 January 2026, and their first reports to HMRC for the 2026 calendar year are due by 31 May 2027. India’s international exchange date is reported differently, so check official sources.
Do I have to report Indian crypto gains on my UK tax return?
If you are UK tax resident, yes. Gains on disposals of crypto abroad are generally taxable in the UK, converted to pounds, with possible relief for Indian tax under the treaty or foreign tax credit rules. Take UK advice.
Will CARF report my wallet balance?
CARF reports transaction totals by type, such as exchanges and transfers, not your balance. Details are in the OECD framework and HMRC guidance.
What if I moved to the UK recently?
Tell your exchange your correct tax residence and check the rules for new arrivals with a UK adviser, because special regimes can apply.
Final word
Halverton & Co. is an Indian law firm advising UK companies, founders, investors and law firms on Indian law, including cross-border tax and compliance for UK residents and NRIs with Indian crypto accounts, virtual digital asset regulation and investor advisory. We practise in Jharkhand, Maharashtra and before the Supreme Court of India, and work alongside your UK solicitors, who advise on English law. Halverton & Co.: Where tech needs law! If you have a question about Indian law, write to us at office@halvertonandco.com, or get in touch.
This article reflects developments reported up to 31 October 2026. It is for general information only, is not legal advice, and does not create a solicitor-client relationship. Halverton & Co. is an Indian law firm, is not authorised or regulated by the Solicitors Regulation Authority, and does not advise on English law; UK-law points should be confirmed with UK advisers.
Sources
Related practice area
Crypto, Web3 & Digital Assets
Advice for virtual digital asset businesses on registration, reporting and structure.
View the practice areaComments
No account needed. Comments are reviewed before they appear, so yours will show here once approved. Please do not share confidential details or describe your own legal matter: replies are general discussion, not legal advice, and do not create an advocate-client relationship. For your own situation, write to office@halvertonandco.com.