Key takeaways
- Many NRI notices follow simple errors: wrong residential status, unreported Indian gains, TDS mismatches, poor cost records and missed replies.
- NRIs are taxed in India on Indian-source income, including gains on Indian exchanges in some cases, at 30%.
- An Indian citizen who is not taxed elsewhere and has Indian income above ₹15 lakh can be a deemed resident.
- If a notice arrives, read the deadline, gather records, work out your status and reply through the portal with advice.
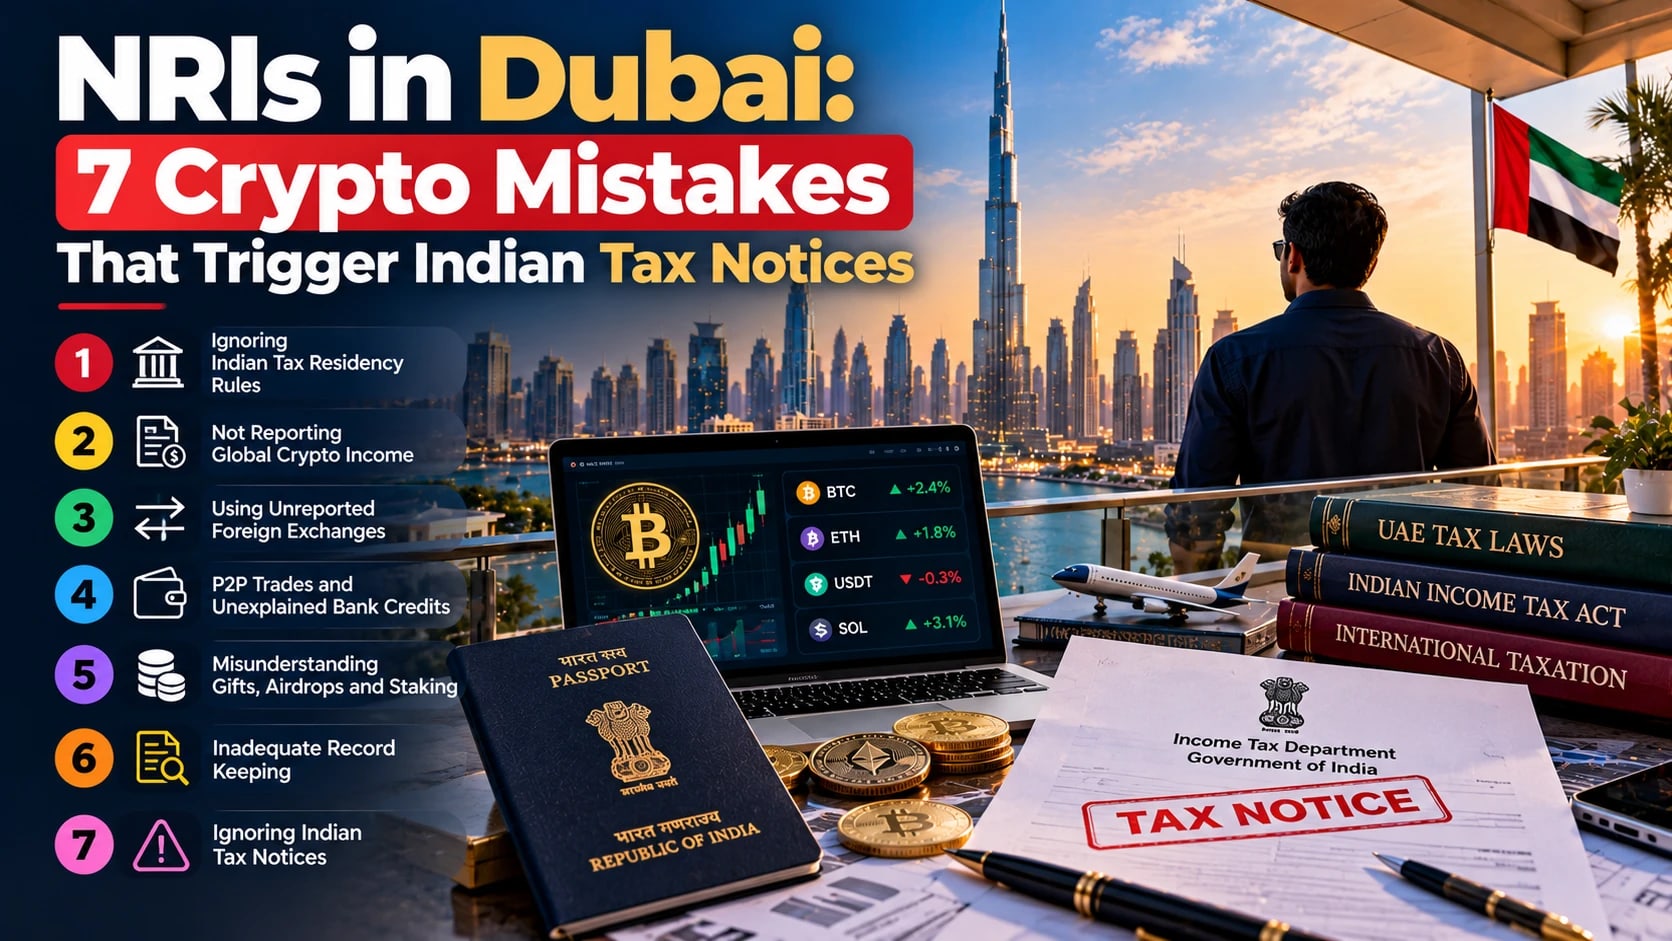
An NRI crypto tax notice often arrives after a simple mistake, not after fraud. Indians living in Dubai assume that the UAE’s lack of income tax means that no tax is due anywhere, or that Indian exchanges will not report them. Indian tax authorities now receive data from exchanges and match it with returns, so errors show up. Seven mistakes cause most of the trouble.
This guide explains each mistake, why it triggers a notice, how to avoid it and what to do if you have received one. It is general information for NRIs. Whether you are an NRI for tax purposes depends on your days in India, so check your own status. UAE-based advisers cannot advise on Indian tax, so take Indian tax advice for your return and for any notice.
Mistakes 1 to 3: residency and reporting
Mistake one: assuming you are an NRI without counting days. India taxes residents on global income and non-residents on Indian income only. You are a resident if you stay in India for 182 days or more in a year, or 60 days or more in the year and 365 days or more in the preceding four years, with longer limits for Indian citizens who visit but a reduced 120-day limit if your Indian income is above ₹15 lakh. Frequent visits can make you resident without noticing. Residence errors are the most common cause of an NRI crypto tax notice.
| Mistake | Why it triggers a notice | Fix |
|---|---|---|
| 1. Not counting days in India | Wrong residential status | Keep a travel diary |
| 2. Missing deemed residence | High Indian income and no tax elsewhere | Check the rule yearly |
| 3. Not reporting Indian gains | Exchange data does not match the return | Report all Indian transfers |
| 4. Ignoring TDS mismatches | TDS credit with no sale in the return | Reconcile your tax statement |
| 5. Poor records | Full proceeds assessed if cost cannot be proved | Use a ledger and tools |
| 6. Gifts and foreign platforms | Overlooked taxable events and foreign assets | Take advice on gifts and disclosure |
| 7. Ignoring notices | Assessment on the department’s information | Keep portal contacts current and reply on time |
Mistake two: overlooking deemed residence. An Indian citizen who is not liable to tax in any other country, and has Indian income above ₹15 lakh, is treated as a resident but not ordinarily resident. Since the UAE has no personal income tax, many NRIs in Dubai are close to this line. Check the rule and its counterpart in the Income-tax Act, 2025. A mistaken NRI crypto tax notice position can lead to demands for tax on global income.
Mistake three: not reporting Indian crypto gains. Even an NRI is taxed in India on Indian-source income, including gains from transfers on Indian exchanges in some cases, at 30% with no deduction except cost. Some NRIs treat Indian exchange activity as tax-free because they live abroad. The exchange reports your trades and TDS, and a return that omits them invites a notice.
Mistakes 4 and 5: Indian exchanges, TDS and records
Mistake four: ignoring TDS mismatches. When you sell on an Indian exchange, 1% tax may be deducted at source and credited to your PAN. If your return does not show the sale but your tax credit statement shows the TDS, the system flags the mismatch. Check your annual tax statement against your return, and include all transfers. Make sure your PAN, address and status are correct with the exchange.
Mistake five: keeping poor records. The law allows only the cost of acquisition as a deduction, so you need to prove cost for each coin, with dates, quantities and values in rupees. Many traders lose track after swaps between coins, transfers between wallets and bridging, and have no clear cost basis. Without records, the tax officer may assess the full proceeds as gain. Use a crypto tax tool, and keep exchange statements and wallet histories.
Both mistakes become more visible with reporting. India’s rules require reporting entities to file statements of crypto transactions, and the tax department can compare them with returns. The Central Board of Direct Taxes issued a guidance note in July 2026 on this reporting. If your data and your return disagree, a notice is likely. The fix is to reconcile before you file.
Mistakes 6 and 7: gifts, foreign platforms and ignoring notices
Mistake six: treating gifts and foreign platform activity as invisible. Gifts of crypto may be taxable in the hands of the receiver if the value exceeds a limit and the donor is not a relative. Transfers between your own wallets are not gifts, but moves to other people may be. Crypto held on foreign platforms is outside Indian exchange reports today, but resident Indians must disclose foreign assets, and the UAE’s participation in the Crypto-Asset Reporting Framework means data may flow to India from 2028, as reported.
Mistake seven: ignoring a notice or reply deadline. Notices from the tax department may arrive by email or on the e-filing portal, and may be missed if your email or address is out of date. A notice that is not answered within the time given can lead to an assessment based on the department’s information, with penalties and interest. Keep your contact details current on the e-filing portal, and check it regularly.
A related error is relying on social media advice. Posts that say that NRIs pay no tax on crypto, or that UAE residency removes all Indian tax, oversimplify. Your status, your sources of income and the exchange you use all matter. If an NRI crypto tax notice arrives, the cost of getting the facts wrong is high, so check claims against the law or with an adviser.
What to do if you receive a notice
Do not panic and do not ignore it. Read the notice to see its section, the year, the information it asks for and the deadline. Notices can be a query about a mismatch, a request for information, a notice of reassessment or a demand. Log in to the e-filing portal, download the notice and any attached data, and note the deadline for the response.
Gather your records: your passport and travel history, proof of residence in Dubai, your PAN and address details, exchange statements, wallet histories, bank statements and your tax returns. Work out your residential status for the year concerned and reconstruct your crypto transactions. Prepare a clear reply with supporting documents. If you made an error, consider whether an updated return is possible, and pay the tax due with interest. Good records decide the outcome of an NRI crypto tax notice.
Take professional help early. An Indian chartered accountant or tax lawyer can draft the reply, appear before the officer and advise on penalties. Keep copies of everything and respond through the portal in the way the notice requires. If the officer’s order is wrong, you may appeal. Acting promptly and with good records usually leads to a better result than silence.
Next steps and quick answers
Before the next filing season, work out your residential status for each year, reconcile your exchange data with your tax credit statement, rebuild your cost records, update your contact details on the e-filing portal and take advice on your Indian and foreign assets. If you have a notice, respond on time with documents. This is general information, not tax advice.
Related reading: moved to Dubai for crypto: India may still tax you, is crypto tax-free in Dubai for Indians?, what CARF means for Indian expats, the crypto nudge email from the tax department, returning to India from Dubai with crypto, crypto tax in India: 30% and 1% TDS and what Budget 2026 changed for crypto tax; also rent and FD interest tax for NRIs in Dubai and why crypto losses cannot be set off in India; also CARF reporting for the UAE and India.
Quick answers
Why do NRIs get crypto tax notices in India?
Common reasons are wrong residential status, unreported Indian crypto gains, mismatches between TDS credits and returns, missing records of cost, and failure to respond to earlier notices. Exchange data is matched with returns.
Do NRIs pay tax on crypto in India?
NRIs are taxed in India on income that arises or is received in India, which can include gains on Indian exchanges, at 30%. Residents and deemed residents are taxed on global income. Your status decides.
What should I do if I get an NRI crypto tax notice?
Read it, note the deadline, gather your records, work out your residential status and reply through the portal with documents. Take advice from an Indian tax professional quickly.
Can I file an updated return if I find an error?
The law allows updated returns within a time limit, with additional tax. Take advice before filing, because the conditions and cost depend on your facts.
Does the UAE tell India about my crypto?
The UAE has committed to CARF, with data collection from 2027 and first exchange in 2028, as reported. Indian exchanges already report domestically.
Final word
Halverton & Co. is an Indian law firm advising NRIs, founders, investors and businesses in Dubai and across the UAE on Indian law, including cross-border tax and compliance for NRIs and Indians in the UAE, virtual digital asset tax, and tax notice and dispute advisory. We practise in Jharkhand, Maharashtra and before the Supreme Court of India, and work alongside UAE-licensed counsel, who advise on UAE law. Halverton & Co.: Where tech needs law! If you have a question about Indian law, write to us at office@halvertonandco.com, or get in touch.
This article reflects developments reported up to 31 October 2026. It is for general information only, is not legal advice, and does not create an advocate-client relationship. Halverton & Co. is an Indian law firm and does not advise on UAE law; UAE-law points should be confirmed with UAE-licensed counsel.
Sources
Related practice area
Crypto, Web3 & Digital Assets
Advice for virtual digital asset businesses on registration, reporting and structure.
View the practice areaComments
No account needed. Comments are reviewed before they appear, so yours will show here once approved. Please do not share confidential details or describe your own legal matter: replies are general discussion, not legal advice, and do not create an advocate-client relationship. For your own situation, write to office@halvertonandco.com.