Key takeaways
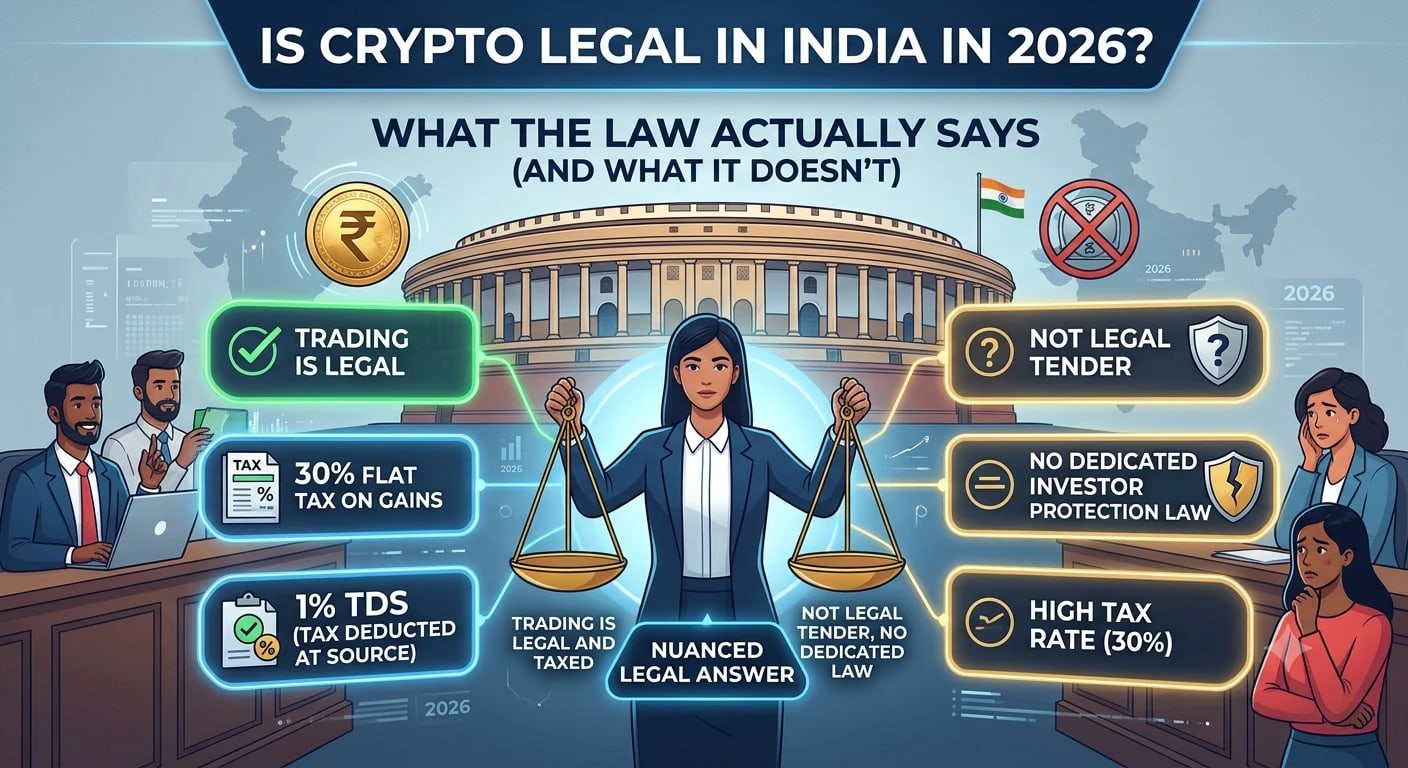
- Buying, holding and selling crypto is legal in India; the Supreme Court struck down the RBI’s 2018 banking restriction in March 2020.
- Gains are taxed at a flat 30% with only cost deductible, and a 1% TDS applies on transfers; Budget 2026 kept both and added reporting penalties.
- Crypto is not legal tender, there is no dedicated crypto law, and no regulator protects investors if an exchange fails.
- Use FIU-registered platforms, keep full records and treat legal as different from safe.
Is crypto legal in India? Yes, in the sense that buying, holding and selling crypto is not banned, and gains are taxed. No, in the sense that crypto is not legal tender, no dedicated law regulates it and no regulator protects investors if an exchange fails. That nuanced answer is the honest one, and it matters because many Indians treat “not banned” as “safe”.
This guide sets out what the law says in 2026: the Supreme Court’s 2020 ruling, the tax rules, the anti-money laundering regime, what is still missing, and the practical steps that follow. It is general information for Indian investors and founders. Always check current rules before you act, because crypto policy in India changes through tax and compliance notifications rather than a single statute.
The short answer
India has never passed a law that bans crypto. The Reserve Bank of India tried to cut crypto businesses off from banks in 2018, but the Supreme Court struck that circular down in March 2020 in Internet and Mobile Association of India v. Reserve Bank of India, mainly on proportionality grounds. Since then, individuals and companies have been free to trade, and the government has chosen to tax and monitor crypto instead of prohibiting it.
So when people ask whether crypto is legal in India, the accurate reply is that trading is lawful and regulated for tax and anti-money laundering purposes, but it sits in a legal grey area on almost everything else. There is no statute that defines your rights as a crypto holder, no licensing regime for exchanges and no compensation scheme. Legal does not mean protected.
Crypto is also not legal tender. Only the rupee, issued under the Reserve Bank of India Act, 1934, can be forced on a creditor as payment. A shop may choose to accept crypto, but nobody has to, and crypto is not treated as currency. For tax, the law calls it a virtual digital asset, a label that says how it is taxed and nothing more about its legal status.
What the law says
Tax is where the law is clearest. Since the Finance Act, 2022, income from transferring a virtual digital asset is taxed at a flat 30% under Section 115BBH of the Income-tax Act, 1961, with no deduction except the cost of acquisition, and losses cannot be set off against other income. A 1% tax deducted at source applies on transfers above the thresholds under Section 194S. These rules now sit in the Income-tax Act, 2025, which took effect on 1 April 2026. That is the legal basis behind the answer to is crypto legal in India: lawful, taxed and monitored.
Budget 2026 kept the 30% rate and the 1% TDS, and added sharper penalties for reporting entities. Reports say the penalties are ₹200 a day for continuing failure to file a statement and ₹50,000 for incorrect information that is not corrected, effective from 1 April 2026, under the crypto-asset reporting provision of the 2025 Act. Check the Finance Act text for the exact section.
| Question | Position in 2026 | Source |
|---|---|---|
| Is trading legal? | Yes, not banned; the 2018 RBI banking restriction was struck down in 2020 | Supreme Court, March 2020 |
| How are gains taxed? | Flat 30%, only cost of acquisition deductible, no loss set-off | Section 115BBH, now in the Income-tax Act, 2025 |
| Is there TDS? | 1% on transfers above the thresholds | Section 194S and its successor |
| Is crypto legal tender? | No, only the rupee is | Reserve Bank of India Act, 1934 |
| Who supervises exchanges? | FIU-IND for anti-money laundering; no investor protection regulator | PMLA notification, March 2023 |
The second pillar is anti-money laundering. A March 2023 notification brought virtual digital asset service providers into the Prevention of Money Laundering Act, 2002. Exchanges and similar platforms must register with the Financial Intelligence Unit, verify customers, keep records and report suspicious transactions. FIU-IND has also issued notices to offshore platforms serving Indian users. This is the closest India has to a licensing regime, and it is about compliance, not investor protection.
What the law does not say
There is no crypto statute. The government released no draft bill after years of talk, and a discussion paper that was meant to set out a policy has not turned into law. The Reserve Bank has repeatedly voiced concerns about financial stability, and officials have suggested that a coordinated global approach would be better. This leaves a vacuum in which tax and anti-money laundering rules fill the space that a regulator would normally fill. This is the part of is crypto legal in India that most explainers skip.
No regulator oversees crypto products. The Securities and Exchange Board of India does not regulate crypto assets unless a token is itself a security, and the Reserve Bank does not supervise exchanges. Bank deposit insurance does not cover crypto balances. If an exchange is hacked or fails, as WazirX was after its 2024 hack, recovery depends on the exchange’s own restructuring and on courts, not on a statutory compensation scheme.
Consumer law offers limited help. The Consumer Protection Act, 2019 can apply to unfair trade practices by a service provider, and criminal law covers fraud, but there is no specific disclosure or custody standard for crypto businesses. A buyer who loses money to a scam or an exchange failure must rely on general civil and criminal remedies, which are slow and uncertain. That gap is why the question of whether crypto is legal in India needs a careful answer.
Risks and practical steps
Use platforms that are registered with FIU-IND and publish clear terms, and avoid unregistered offshore sites that target Indian users. Registration is a compliance marker, not a guarantee of safety. Keep only what you need on any exchange, consider self-custody for larger holdings, and use strong security. Never share seed phrases, and be sceptical of promised returns, since fraud is the biggest practical risk. Anyone asking is crypto legal in India should also ask which platforms are lawful to use.
Keep tax records from the start. Maintain a log of every purchase, sale, transfer and fee, because the cost of acquisition is the only deduction. Report gains in the schedule for virtual digital assets in your return, and check TDS credits against your tax statement. Exchanges now report to the tax department, so mismatches are visible. If you have not reported earlier gains, take advice on correcting your return before a notice arrives.
Understand the banking side. Banks have sometimes frozen accounts after receiving funds from peer-to-peer crypto trades that are linked to a fraud complaint. Prefer exchange deposits and bank transfers in your own name, keep proof of source of funds and respond quickly to bank queries. For businesses, take advice on accounting, GST and contracts before accepting crypto, because the rules are not written for it.
Next steps and quick answers
Before you invest in crypto in India, decide how much you can afford to lose, choose a registered platform, set up record keeping and read the tax rules. Treat any claim that India has banned crypto, or that the government has approved it, with caution. The law is still evolving, and a policy paper, a Budget change or a court ruling can shift the position. Review your position at least once a year. Revisit the question is crypto legal in India whenever a Budget or court ruling changes the rules.
Related reading: RBI’s stance on crypto, India’s shelved crypto policy paper, crypto tax in India: 30% and 1% TDS, FIU-IND registration for crypto businesses, can a bank close your account for crypto?, what Budget 2026 changed for crypto tax and whether WazirX and CoinDCX are legal; also Web3 regulations in India and crypto lawyer in India: eight legal problems.
Quick answers
Is crypto legal in India in 2026?
Yes, trading and holding are legal and taxed, but crypto is not legal tender and no dedicated law or regulator protects investors. Exchanges must register with FIU-IND for anti-money laundering purposes.
Has the Reserve Bank banned crypto in India?
No. The Supreme Court struck down the Reserve Bank’s 2018 banking restriction in March 2020. The Reserve Bank has voiced concerns but has not imposed a legal ban since.
How is crypto taxed in India?
Gains are taxed at a flat 30% with no deduction other than cost, and a 1% TDS applies on transfers. Budget 2026 kept these rates and added reporting penalties.
Can I be arrested for owning crypto in India?
Owning crypto is not a crime in India. Arrests arise from fraud, money laundering or other offences, not from holding or trading crypto that is declared and taxed.
Do I have to declare crypto in my tax return?
Yes. Report gains from the transfer of virtual digital assets in the relevant schedule, and report foreign crypto assets if you are a resident.
Final word
Halverton & Co. is an Indian law firm advising founders, startups, technology companies and investors on Indian law, including virtual digital asset tax, anti-money laundering compliance, technology law, and startup and investor advisory. We practise in Jharkhand, Maharashtra and before the Supreme Court of India, and act as fractional legal counsel for technology-driven businesses. Halverton & Co.: Where tech needs law! If you have a question about Indian law, write to us at office@halvertonandco.com, or get in touch.
This article reflects developments reported up to 31 October 2026. It is for general information only, is not legal advice, and does not create an advocate-client relationship. Halverton & Co. is an Indian law firm.
Sources
Related practice area
Crypto, Web3 & Digital Assets
Advice for virtual digital asset businesses on registration, reporting and structure.
View the practice areaComments
No account needed. Comments are reviewed before they appear, so yours will show here once approved. Please do not share confidential details or describe your own legal matter: replies are general discussion, not legal advice, and do not create an advocate-client relationship. For your own situation, write to office@halvertonandco.com.