Key takeaways
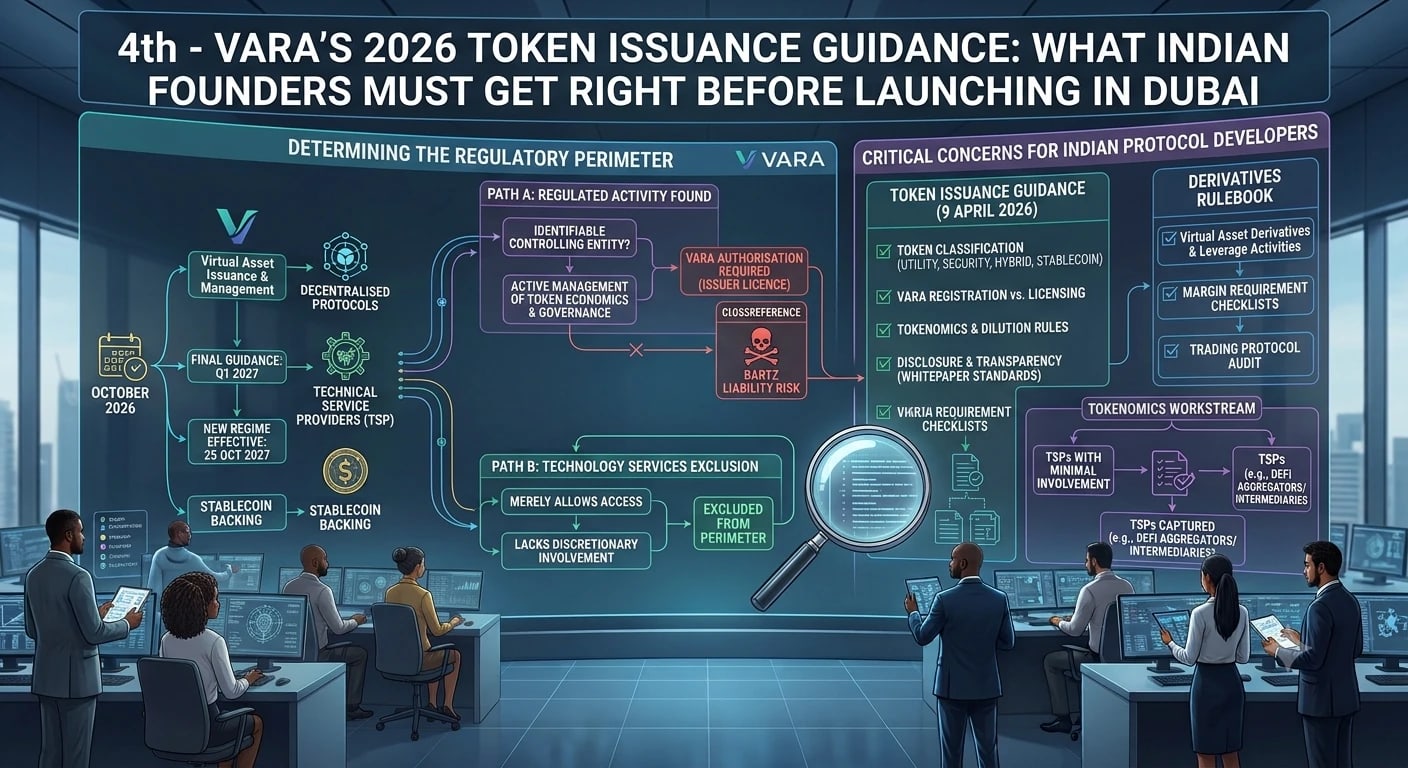
- VARA published its Virtual Asset Issuance Guidance on 9 April 2026 (EN 516 VER1), which commentary describes as interpreting the existing Issuance Rulebook.
- Reports describe a three-tier classification of tokens and disclosure and compliance expectations; we did not read the full guidance.
- The derivatives framework appears to sit in the Exchange Services Rulebook v2.1, a separate instrument.
- VARA approval does not answer Indian tax, FEMA or FIU-IND questions for Indian founders.
A token launch in Dubai used to depend on reading the Virtual Assets Issuance Rulebook and guessing how VARA would apply it. VARA token issuance guidance 2026 changes that. VARA published its Virtual Asset Issuance Guidance on 9 April 2026, and law-firm commentary describes it as the first detailed guidance of its kind, setting out how tokens are classified and who is responsible for what at issuance.
For Indian founders, the guidance matters because a launch from Dubai to Indian and global buyers brings together Dubai rules, Indian tax and foreign exchange law, and marketing risk. This guide explains what VARA token issuance guidance 2026 says on the points we could confirm, how the issuance rulebook works, what the separate derivatives changes are, and a checklist for founders. UAE-law points should be confirmed with UAE-licensed counsel.
What VARA published in April 2026
VARA published the Virtual Asset Issuance Guidance on 9 April 2026, as document EN 516 VER1 on its rulebooks site. Commentary from firms such as Hadef & Partners and Al Tamimi, and press from the Emirates News Agency, describes the guidance as interpreting the existing Virtual Assets Issuance Rulebook, not creating new law. The aim is to make clear how VARA applies the rulebook in practice.
Reports say it sets out three issuance pathways and a three-tier classification of tokens, and that it explains licensing requirements, whitepaper disclosures and extra compliance requirements for issuers of asset-referenced virtual assets. We did not open the full guidance, so the details of each tier should be read in the original before any structuring decision.
VARA’s regime covers virtual asset activity in and from Dubai, including free zones but excluding the DIFC, which is regulated by the DFSA. A token offered from the DIFC follows a different regime. Founders who see VARA token issuance guidance 2026 as a general UAE rule should recheck which regulator applies to their entity and offer.
It helps to read the guidance alongside the underlying rulebook and VARA’s other publications, for example its marketing and compliance rules. The guidance is a statement of how VARA reads its own rules, so applying VARA token issuance guidance 2026 means using it as the lens for the Issuance Rulebook, not as a replacement. Keep a dated copy of each document you rely on, since VARA publishes new versions, and note the version number in your compliance file.
How token classification and approval work
The Issuance Rulebook, introduced in 2025, requires issuers to obtain VARA’s approval for each token before it is offered where the rules apply, and to publish a whitepaper with disclosures. Issuers must also meet governance, conduct and, for asset-referenced tokens, additional requirements about the underlying assets. The issuance rulebook is the legal source, and the guidance explains how VARA reads it.
Classification comes first. A token can represent a utility, a payment instrument, a claim on an asset or something that looks like a security. Where a token is a security or commodity, the UAE Securities and Commodities Authority may also be relevant, so overlap between regulators is possible. A founder who treats classification as a marketing label instead of a legal question risks launching under the wrong regime.
| Step | What to prepare | Why |
|---|---|---|
| Classify the token | A written classification analysis against VARA’s categories | Wrong classification can mean launching under the wrong regime |
| Choose the issuing entity | A licensed or registered Dubai entity with real substance | Supports approval and avoids Indian tax residence questions |
| Prepare the whitepaper | Accurate, complete disclosures that match how the token works | VARA expects disclosure and approval before offering where the rules apply |
| Plan marketing | Approved wording and no return promises | Promoting virtual assets without the required approval can be an offence |
| Plan banking and custody | Bank accounts and custody for proceeds and any reserve assets | A launch can stall without them |
The practical effect of VARA token issuance guidance 2026 is that early-stage planning should include the classification analysis, the choice of issuing entity, the whitepaper and the approval timeline. A token that cannot be explained clearly in the whitepaper is unlikely to be approved quickly. Allow for questions from VARA and build time for them into the launch plan.
Derivatives and the exchange rules
VARA also changed its derivatives rules in 2026, but separately. The derivatives framework appears to sit in VARA’s Exchange Services Rulebook, version 2.1, which reports say took effect on 31 March 2026. It creates a path for licensed exchange operators to offer derivatives with explicit approval and within a tighter supervisory perimeter. Coverage of the issuance guidance did not mention derivatives content, so we treat them as separate instruments.
For a token issuer, this matters in two ways. First, a token that later trades on a licensed exchange will be subject to that exchange’s listing and market rules. Second, if a founder plans margin or derivative products linked to the token, those are regulated exchange-side activities that need the exchange operator to hold the right approval. The issuer cannot simply create a derivative product around its own token.
Check the current versions of each rulebook before launch. VARA updates its rulebooks, and the version in force on the launch date governs. Keep a dated copy of the version you relied on, with your analysis, in your compliance file.
What Indian founders must get right
Choose the right entity. The issuer should usually be a properly licensed or registered Dubai entity with real substance, not a shell. Think about where the team sits, where decisions are made and which entity contracts with buyers. A Dubai company run from India can face Indian tax residence questions based on place of effective management, so document where decisions are taken.
Get the whitepaper and the marketing right. Disclosures should be accurate, complete and consistent with how the token actually works. Marketing in Dubai is regulated, and promoting virtual assets without the required licence or approval can be an offence even if the company is incorporated elsewhere. Avoid return promises, avoid targeting Indian retail buyers without advice and keep community channels consistent with the whitepaper. VARA token issuance guidance 2026 is best read together with VARA’s marketing rules.
Plan for the buyers. If tokens are offered to people in India, remember that India has no approval route for token offerings and treats virtual digital asset gains as taxable at a flat 30%, with a 1% TDS on transfers. FEMA governs funds going out of India and any overseas investment by an Indian company. FIU-IND registration may apply to platforms serving Indian users. Founders who skip these checks can launch a compliant Dubai token and still create Indian liabilities.
Banking and custody should be planned early. Token issuers need bank accounts for fiat proceeds and custody arrangements for any reserve or underlying assets, and banks apply their own risk appetite to crypto business. A founder who has a VARA approval path but no bank may be unable to launch. Raise the question with prospective banks and custodians while the classification and whitepaper are being prepared.
Indian-law checks, remedies and quick answers
Before launch, build a checklist: classification memo, issuing entity and substance, whitepaper review, VARA approval path, marketing plan, banking and custody, Indian tax and FEMA review, FIU-IND analysis for any Indian-facing service and a record of each rulebook version relied on. Ask UAE counsel to confirm the VARA points and Indian counsel to confirm the India points, and have the two coordinate. Do not take customer funds or promote the token before the required approvals are in place. If VARA raises questions, respond promptly and in full. If you have already launched without the right approvals, stop the offer, take advice and consider approaching VARA, because voluntary correction is generally better than being found. Review the position each time the token’s features change, since adding yield, redemption or asset backing can change the classification. Reading VARA token issuance guidance 2026 closely at the start is much cheaper than rewriting a launch after the fact.
Related reading: the VARA and Securitize tokenisation MoU, DMCC and VARA licences compared, launching a token from Dubai with Indian investors, VARA licence, Indian users and FIU-IND registration, tokenized real estate in Dubai for Indian investors, VARA and UAE corporate tax for Indian-founded firms and Coinbase’s Abu Dhabi hub and the ADGM route; also smart contract liability for Indian developers and DIFC versus ADGM for crypto tokens in 2026; also the GENIUS Act and stablecoins from 18 January 2027 and whether crypto is legal in Dubai in 2026.
Quick answers
What is VARA’s 2026 token issuance guidance?
VARA published its Virtual Asset Issuance Guidance on 9 April 2026. Commentary says it explains how VARA applies the existing Issuance Rulebook, including a three-tier classification of tokens and disclosure and compliance expectations.
Does an Indian founder need VARA approval to launch a token in Dubai?
If the token is issued in or from Dubai outside the DIFC and falls within VARA’s issuance rules, approval and a whitepaper are required. The exact requirements depend on classification, so take UAE advice before launch.
Does Dubai approval cover offers to buyers in India?
No. A VARA approval does not answer Indian tax, FEMA or other Indian-law questions, and India has no approval route for token offerings. Indian founders and investors need separate Indian advice.
Where is the derivatives framework?
Our research found it in VARA’s Exchange Services Rulebook, version 2.1, reported to be effective from 31 March 2026, as a separate instrument from the issuance guidance. Check the current rulebooks before relying on it.
Does a VARA approval cover Indian law?
No. It does not answer Indian tax, FEMA or other Indian-law questions, and India has no approval route for token offerings.
Final word
Halverton & Co. is an Indian law firm advising NRIs, founders, investors and businesses in Dubai and across the UAE on Indian law, including token launches, FEMA structuring, FIU-IND registration and Indian tax for Indian-founded Web3 businesses operating from Dubai. We practise in Jharkhand, Maharashtra and before the Supreme Court of India, and work alongside UAE-licensed counsel, who advise on UAE law. Halverton & Co.: Where tech needs law! If you have a question about Indian law, write to us at office@halvertonandco.com, or get in touch.
This article reflects developments reported up to late October 2026. It is for general information only, is not legal advice, and does not create an advocate-client relationship. Halverton & Co. is an Indian law firm and does not advise on UAE law; UAE-law points should be confirmed with UAE-licensed counsel.
Sources
Related practice area
Crypto, Web3 & Digital Assets
Advice for virtual digital asset businesses on registration, reporting and structure.
View the practice areaComments
No account needed. Comments are reviewed before they appear, so yours will show here once approved. Please do not share confidential details or describe your own legal matter: replies are general discussion, not legal advice, and do not create an advocate-client relationship. For your own situation, write to office@halvertonandco.com.