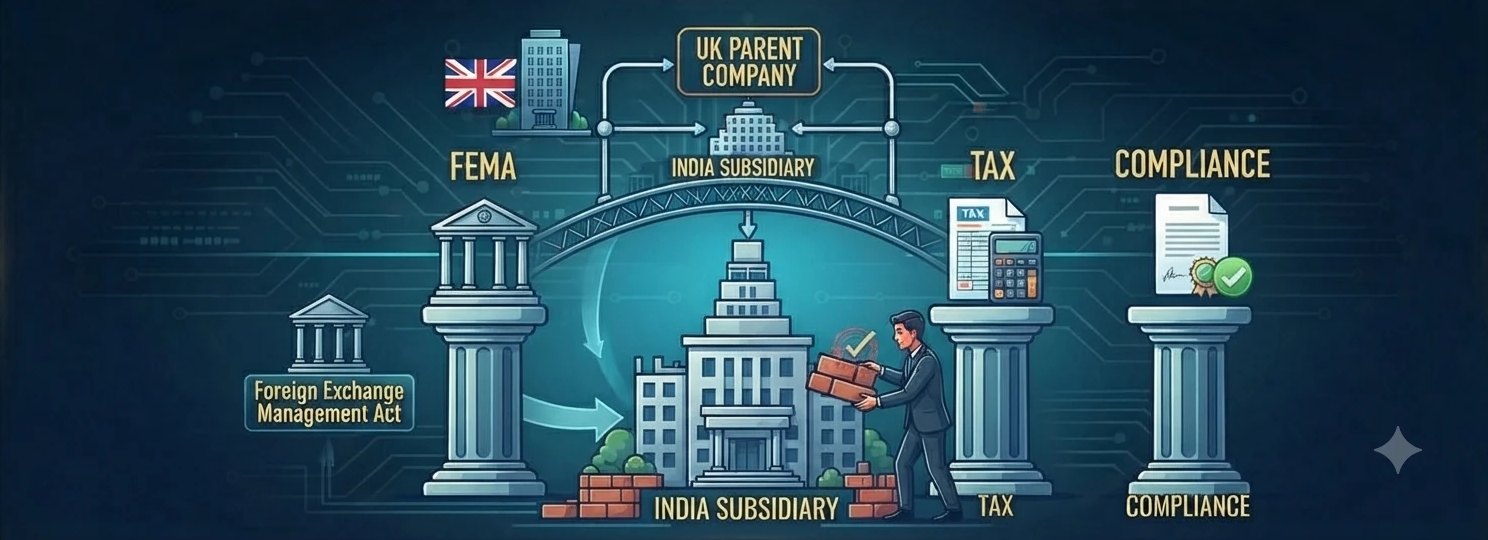
For many UK businesses, India starts as a cost-saving idea, a development team or a back office, and grows into something bigger: customers, a brand, a second home market. At some point, contractors and outsourcing arrangements stop being enough, and the business needs its own Indian company.
This guide explains how to set up a company in India from the UK: choosing the right structure, incorporation and directors, foreign investment rules, tax and transfer pricing under the India-UK tax treaty, and the ongoing compliance calendar. The UK-side tax and company law points should be checked with UK advisers.
Choosing the right structure
Most UK businesses set up their Indian operation as a private limited company under the Companies Act, 2013. It offers limited liability, can be wholly owned by the UK parent, and is the structure Indian banks, landlords, employees and customers know best. A private company needs at least two shareholders and two directors, so the UK parent typically holds almost all the shares, with a nominal holding by an affiliate or individual.
Alternatives exist but are narrower. A limited liability partnership can accept foreign investment only in sectors where 100% foreign investment is allowed under the automatic route without performance-linked conditions. Liaison and branch offices need RBI approval and suit specific purposes, such as representation or particular projects, rather than a full operating business.
The UK-India trade deal, in force since 15 July 2026, also improves services access in some sectors without requiring a local presence, so it’s worth asking whether you need an Indian company at all for the first phase; see our legal checklist for the UK-India trade deal. For an employed team, an operational centre or Indian customers, the answer is usually yes.
Incorporation and directors
Every Indian company must have at least one director who stayed in India for at least 182 days in the previous calendar year, under Section 149(3) of the Companies Act. UK companies usually appoint a senior Indian employee or a trusted local professional as the resident director, alongside directors from the UK.
Incorporation is done online with the Ministry of Corporate Affairs: digital signature certificates and director identification numbers, name reservation, and the incorporation filing with the memorandum and articles of association. Documents from the UK parent and UK directors usually need to be notarised and apostilled, which is often the slowest step. With documents ready, the incorporation itself commonly takes a few weeks.
Name approval can take more than one attempt, as the Registrar may reject names that are too similar to existing companies or trade marks, so check availability and trade mark conflicts before you file. It’s also sensible to register the Indian company’s name and brand as a trade mark in India early; see our guide to trademark registration for startups in India. After incorporation, the new company obtains its tax registrations (PAN, TAN and GST where applicable), opens a bank account, registers under labour and state laws, and receives its share capital from the UK parent. Banks will carry out detailed checks on the UK parent’s ownership, so have beneficial ownership information ready.
| Step | Detail |
|---|---|
| Structure | Wholly owned private limited company; two shareholders and two directors |
| Resident director | At least one director who stayed in India 182 days or more in the previous calendar year |
| Incorporation | DSCs, DINs, name reservation, MCA filing; apostilled and notarised UK documents |
| Registrations | PAN, TAN, GST where applicable, bank account, labour and state registrations |
| FEMA | Share capital through banking channels; FC-GPR within 30 days of allotment |
Foreign investment and FEMA compliance
Funding from the UK parent is foreign direct investment under the Foreign Exchange Management Act, 1999. Most technology, services and manufacturing sectors permit 100% foreign investment under the automatic route, with no prior approval. Some sectors are capped or need government approval, so confirm your activity first.
Shares must be issued at a price not below fair value, and the company must report the investment to the RBI on Form FC-GPR within 30 days of allotment. Later share issues, transfers and the annual return on foreign liabilities and assets also need to be reported. Late filings can be regularised with a late submission fee, and more serious contraventions compounded, but avoiding them is far cheaper.
Many UK businesses also ask whether they can fund the Indian company with loans instead of share capital. Inter-company loans from a foreign parent are possible under India’s external commercial borrowing framework, but they come with conditions on purpose, cost and reporting, so equity is usually simpler at the start. If any shareholder in the group’s ownership chain is from a country sharing a land border with India, government approval may be needed under Press Note 3, which can affect UK groups with certain international investors. Check the ultimate beneficial ownership early.
Tax, transfer pricing and the India-UK treaty
The Indian subsidiary is taxed in India on its profits. New domestic companies can generally opt for a concessional corporate tax regime at an effective rate of around 25% including surcharge and cess. India’s Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026, so check current section references with your advisers; see our guide to the Income-tax Act 2025 for startups.
Transfer pricing is the main issue for most UK-owned subsidiaries. Services provided by the Indian company to the UK parent, such as software development or back-office support, must be priced at arm’s length, typically on a cost-plus basis, documented in an intercompany agreement and a transfer pricing study, and reported annually. The India-UK double taxation agreement determines how dividends, royalties and fees for technical services paid between the two companies are taxed, and provides relief from double taxation.
Goods and services tax is another early consideration. The Indian company may need GST registration, and services it provides to the UK parent may qualify as exports of services, which affects how GST applies. Getting this right from the first invoice avoids disputes later. Permanent establishment risk works both ways. If UK staff spend long periods in India or conclude contracts there, the UK company itself could be taxable in India. Plan secondments and travel with this in mind, and check how the UK-India Double Contributions Convention applies to staff moving between the countries.
Ongoing compliance, remedies and quick answers
Once you set up a company in India from the UK, expect a steady compliance calendar: statutory audit, annual filings with the Registrar of Companies, board meetings, income tax and transfer pricing filings, GST and payroll withholding returns, labour code compliance since 21 November 2025, and FEMA reporting; see our guide to the new labour codes. Missed filings can lead to penalties and, for directors, disqualification.
If problems arise, most can be fixed: late company filings with additional fees, FEMA defaults through late submission fees or compounding, and tax disputes through appeals or advance pricing agreements. A clear compliance calendar and a reliable local adviser from day one prevent most of them. Related reading: hiring developers in India from the UK, IP assignment for UK start-ups with Indian developers, shutting down a startup legally, and the US-facing version of this guide, setting up an Indian subsidiary of a US company; also selling SaaS to Indian customers from the UK; also seconding UK staff to India; also setting up a Dubai crypto holding company.
Quick answers
Can a UK company own 100% of an Indian company?
Yes, in most sectors, under the automatic route for foreign direct investment.
Does an Indian company need an Indian resident director?
Yes. At least one director must have stayed in India for at least 182 days in the previous calendar year.
How long does it take to set up a company in India from the UK?
With apostilled documents ready, incorporation commonly takes a few weeks, plus time for bank accounts and registrations.
Final word
Halverton & Co. is an Indian law firm that advises on Indian law, including incorporating and maintaining Indian subsidiaries, FEMA reporting and intercompany arrangements. We practise in Jharkhand, Maharashtra and before the Supreme Court of India, and we work alongside your UK solicitors, who advise on English law. Halverton & Co.: Where tech needs law! If you have a question about Indian law, write to us at office@halvertonandco.com, or get in touch.
This article reflects developments reported up to early October 2026. It is for general information only, is not legal advice, and does not create a solicitor-client relationship. Halverton & Co. is an Indian law firm, is not authorised or regulated by the Solicitors Regulation Authority, and does not advise on English law.
Related practice area
Startups & Venture
From incorporation to term sheet. The documents a company needs to be fundable.
View the practice area